
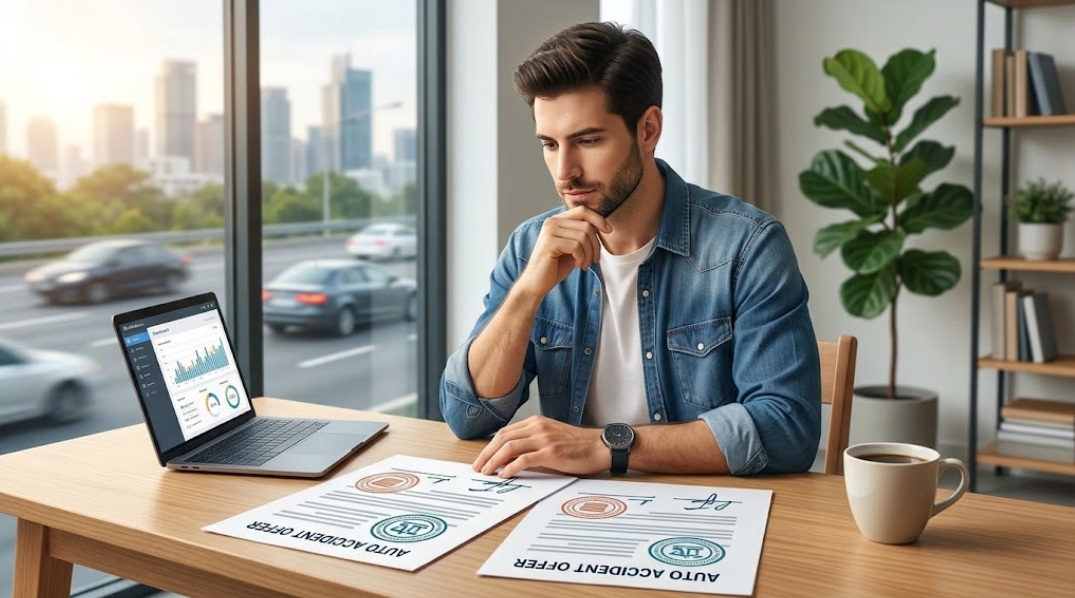
Auto accidents are common in Utah and result in serious injuries and fatalities too. After a car collision, you may file a claim but wonder how settlements work and what amount you’ll receive.
Insurance companies use false tactics to decrease your settlement, and therefore you should be careful before accepting the offer.
This article covers 5 crucial factors that can impact your compensation, legal rights, and overall recovery. You’ll understand how to review the offer before accepting and when to consult with an auto accident lawyer to protect your rights.
1. Know What the Settlement Covers
First, check and make sure that the settlement accounts for the losses connected to your accident. These may include economic and non-economic damages.
Economic damages may include:
- Past and future medical expenses
- Lost wages
- Reduced earning capacity
- Vehicle repairs or replacement
- Towing and rental car costs
Similarly, non-economic damages may include:
- Pain and suffering
- Emotional distress
- Loss of enjoyment of life
Do not focus only on the gross settlement amount. Your actual payment may be lower after attorney fees, case costs, medical liens, and insurance reimbursement. To know that the settlement offer is enough, compare it with your current losses, expected future costs, fault percentage, available insurance, and expected deductions.
2. Understand Your Medical Outlook
Insurers, most of the time, make early offers that look attractive but in reality are not. Do not accept any sort of offer until you know the complete extent of your injuries, recovery, and income loss.
For instance, whiplash or soft tissue injuries can appear later. So, if you settle too early, you may have to pay future treatment costs yourself. Also, discuss Maximum Medical Improvement (MMI) with your doctor and keep records of every sort of medical care, including:
- Hospital and emergency room records
- MRI, CT, and X-ray results
- Doctor reports
- Treatment notes
- Physical therapy records
- Prescription records
- Future treatment recommendations
An insurer may also request an Independent Medical Examination (IME). The IME doctor’s opinion may differ from your treating doctor’s opinion.
3. Check Fault and All Insurance Coverage
Utah uses modified comparative negligence under Utah Code § 78B-5-818. If you are partly at fault, your recovery can be reduced by your percentage of fault, but it should not be above 50%. Exceeding that limit ultimately eliminates your recovery.
An insurer’s fault assessment is not necessarily final. Evidence may support a different assessment. Useful evidence can include police reports, witness statements, dashcam footage, traffic camera footage, and vehicle damage photos.
You should also check all possible insurance coverage. This may include:
- At-fault driver’s liability insurance
- Uninsured motorist coverage
- Underinsured motorist coverage
- Personal Injury Protection (PIP)
- Commercial auto insurance
- Umbrella coverage
Utah requires minimum auto liability limits under Utah Code § 31A-22-304. Your own policy may also provide UM or UIM coverage. Other parties, like other vehicle owners, an employer, or a government entity, may also share responsibility for a Utah car accident. Facts prove this.
4. Read the Release Before Signing
The settlement offer tells you how much the insurer will pay. The release tells you what rights you give up. A release is a legal agreement. It may prevent you from seeking additional compensation for claims covered by the agreement. Before signing, check:
- Who the release covers
- Which claims it releases
- Whether it covers unknown injuries
- Whether medical liens are addressed
- Any indemnity terms
- Any confidentiality terms
Pay close attention to a general release. It may cover claims that you do not know about when you sign. Do not assume you can reopen the claim later if your condition becomes worse.
Also be careful with settlement checks. A check marked as full or final payment may create legal issues if you cash it. Read the check and related documents before depositing it.
5. Calculate Your Net Recovery and Deadline
The settlement amount is not always the amount you will receive. The actual amount you receive may be much less than what you might think because of:
- Attorney fees
- Case expenses
- Medical liens
- Health insurance reimbursement
- Medicare and workers’ compensation reimbursement
Ask for a written settlement statement. It should show the gross settlement, each deduction, and your expected payment. You should also know your legal deadline, as for most Utah personal injury claims, the filing limit is four years. However, property damage claims can have different deadlines.
What to Do Before Accepting the Car Accident Settlement
Here are some important points to consider before you accept a Utah car accident settlement offer presented by insurers:
- Read the offer and release.
- Review your medical treatment and prognosis.
- Calculate your current and future losses.
- Check the fault percentage.
- Identify all available insurance.
- Review medical liens and reimbursement claims.
- Calculate your expected net payment.
- Check your legal deadline.
- Consider consulting with an auto accident lawyer for an in-depth review of the release.
Frequently Asked Questions
Should I accept the first car accident settlement offer?
The first insurance offer is not always the best. So, do not accept it without reviewing what it covers. If it covers your losses and future care expenses, then you can accept it, but that is very rare.
Do medical liens reduce my settlement?
Yes, they can. A health insurer, Medicare, Medicaid, or workers’ compensation program may seek reimbursement for accident-related bills it paid. The amount depends on the specific claim and applicable law.
Can I negotiate a car accident settlement?
Yes. You can respond with evidence supporting your losses, including your medical records, bills, wage records, and property damage records.
Can I settle without going to court?
Yes. Many auto accident claims resolve through negotiations. A lawsuit may become necessary if negotiations fail or a legal deadline approaches.
What happens if my injuries get worse after I settle?
A signed release may prevent you from seeking more compensation for the accident. Future medical costs may then become your responsibility.
Conclusion
A car accident settlement is more than the number on the offer. Before accepting it, review your medical outlook, total losses, fault percentage, insurance coverage, liens, and release. Then calculate your expected net recovery. Do not sign a release before you truly know what rights you are giving up. If you have any doubts in your mind regarding the settlement offer, Hernandez Injury Law offers a free consultation to Utah victims. Contact the firm today to discuss your options.
